Advertorial
That 1.99% Car Loan Isn't As Cheap As It Looks. Here's What Dealers Don't Tell You.
A simple 2-question trick that shows how much of the "cheap" interest is hidden in the car's price, and how to get the best price on the car and the loan.
By Sarah Jones
4 min read
About the author — Sarah Jones has spent more than a decade writing about personal finance for Australian readers, from car loans and insurance to energy bills. She has spoken with dozens of finance brokers and dealership staff about how finance deals really work, and writes plain-English guides that help people check an offer before they sign.
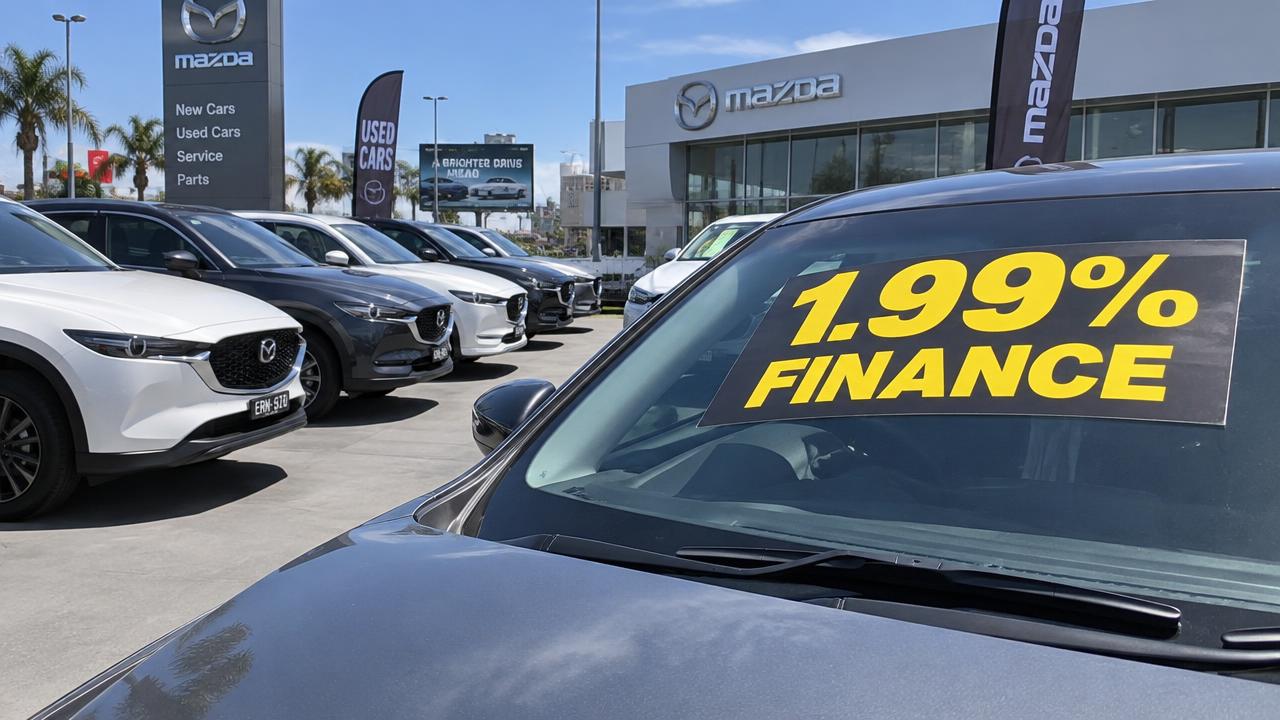
You've seen the signs. "1.99% finance!" in big letters on the windscreen. Sometimes even 0.99%.
It sounds like a bargain. Banks charge a lot more than that for a home loan. So how can a car dealer lend you money that cheap?
The short answer: they usually don't. You just pay for it somewhere else.
How the 1.99% trick works
In the industry it's called subvention. That's a fancy word for "someone pays the lender to make the rate look low."
The lender still needs to make its money. So the car maker or the dealer pays the lender a lump sum to "buy down" the rate. That money has to come from somewhere, and usually it's built into the price of the car.
So when you take the 1.99% deal, you often pay full sticker price, or close to it. The discount you could have haggled for quietly disappears. The interest isn't gone. It's just been moved into the car price, where you can't see it.
Here's the sneaky part. By law, a low advertised rate has to sit next to a "comparison rate", which is meant to show the true cost of a loan. But the comparison rate only counts interest and loan fees. It can't see a finance cost that's hiding in the car's price. So a 1.99% deal can look squeaky clean on paper and still cost you more.
A real-world style example
Say you're looking at a car with a sticker price of $44,990. The dealer offers 1.99% over 5 years.
But if you ask for their best cash price, they'll do it for $39,990. Then you get finance through a broker at 6.99% over 5 years.
| 1.99% dealer deal | Cash price + broker loan | |
|---|---|---|
| Amount borrowed | $44,990 | $39,990 |
| Interest rate | 1.99% | 6.99% |
| Monthly repayment | about $788 | about $792 |
| What you still owe after 2 years | about $27,500 | about $25,600 |
The repayments are almost the same. Over the full 5 years, the total cost comes out roughly even. So that "cheap" 1.99% was never really cheap. You were just paying the interest up front, inside the price.
And look at that last row. Lots of people sell, trade in or refinance their car before the loan is finished. If you do that after 2 years, the cash-price option leaves you owing about $1,900 less.
Example numbers for illustration only. Your price, rate and loan will be different.
The smarter way to buy: 4 simple steps
Most buyers walk in and ask, "What can you do on finance?" That's exactly what the dealer wants. Here's what to do instead.
Ask for the best cash price first.
Tell the salesperson you're paying cash. Ask for their best drive-away price, and get it in writing. Don't mention finance yet.
Now ask about finance on that price.
Once you have the cash price locked in, say: "Actually, what finance can you do on this price?" Watch what happens to that 1.99%. In most cases it vanishes, because the discount and the cheap rate were never both on the table.
Get a second opinion on the loan.
Take your cash price to an independent finance broker. A broker can shop your loan across a big panel of lenders to find a competitive rate for your situation.
Ask the dealer to beat it.
Show the dealer the broker's offer, on the same price, and ask if they can do better. Sometimes they can. Often they can't. Either way, you win, because now you know the real cost.
Where AutoBuddy comes in
Step 3 is where most people get stuck. Who do you even call?
That's what AutoBuddy is for. Answer a few quick questions (it takes about 30 seconds). We'll connect you with a finance broker who compares loans from 40+ lenders on their panel and comes back with options that suit you.
Then you walk into the dealership with your cash price in one hand and a real finance offer in the other. That's how you get the best deal on the car and the loan.
It's free to compare, and checking won't affect your credit score.